Esper never moves money
Your treasury team still sends every payment directly, through your own banking channels. Esper only confirms when the funds arrive.
Bridging should move at lightning speed, but drawdowns still wait days for one bank statement from a broker. Esper plugs your underwriting straight into the source: open banking and crypto-signed surveyor sign-offs on one ledger, across every scheme you fund.
Stop chasing paper · 1:00
Esper doesn't sit between you and your money, and it doesn't make credit decisions. It gives you a far clearer view of every loan, so you can act sooner and spend less on oversight.
Your treasury team still sends every payment directly, through your own banking channels. Esper only confirms when the funds arrive.
The senior lender holds the master override and can freeze or recalibrate at any time. Where there's a mezzanine lender, it holds a sub-override over its own position.
Terms, covenants and approvals stay with your credit team. Esper reports the facts and checks the rules you set.
Cash is confirmed by a live bank feed and every report is fingerprinted, so forged statements and altered reports stand out.
If a developer runs into trouble, you see it as it happens, not at the next site visit or monthly report.
No chasing brokers for statements, no re-keying reports. Your team can oversee more loans for the same cost.
For bridging lenders, all your loans sit on one master dashboard, with only broken conditions and actions due brought forward. That cuts the cost of oversight across the whole book.
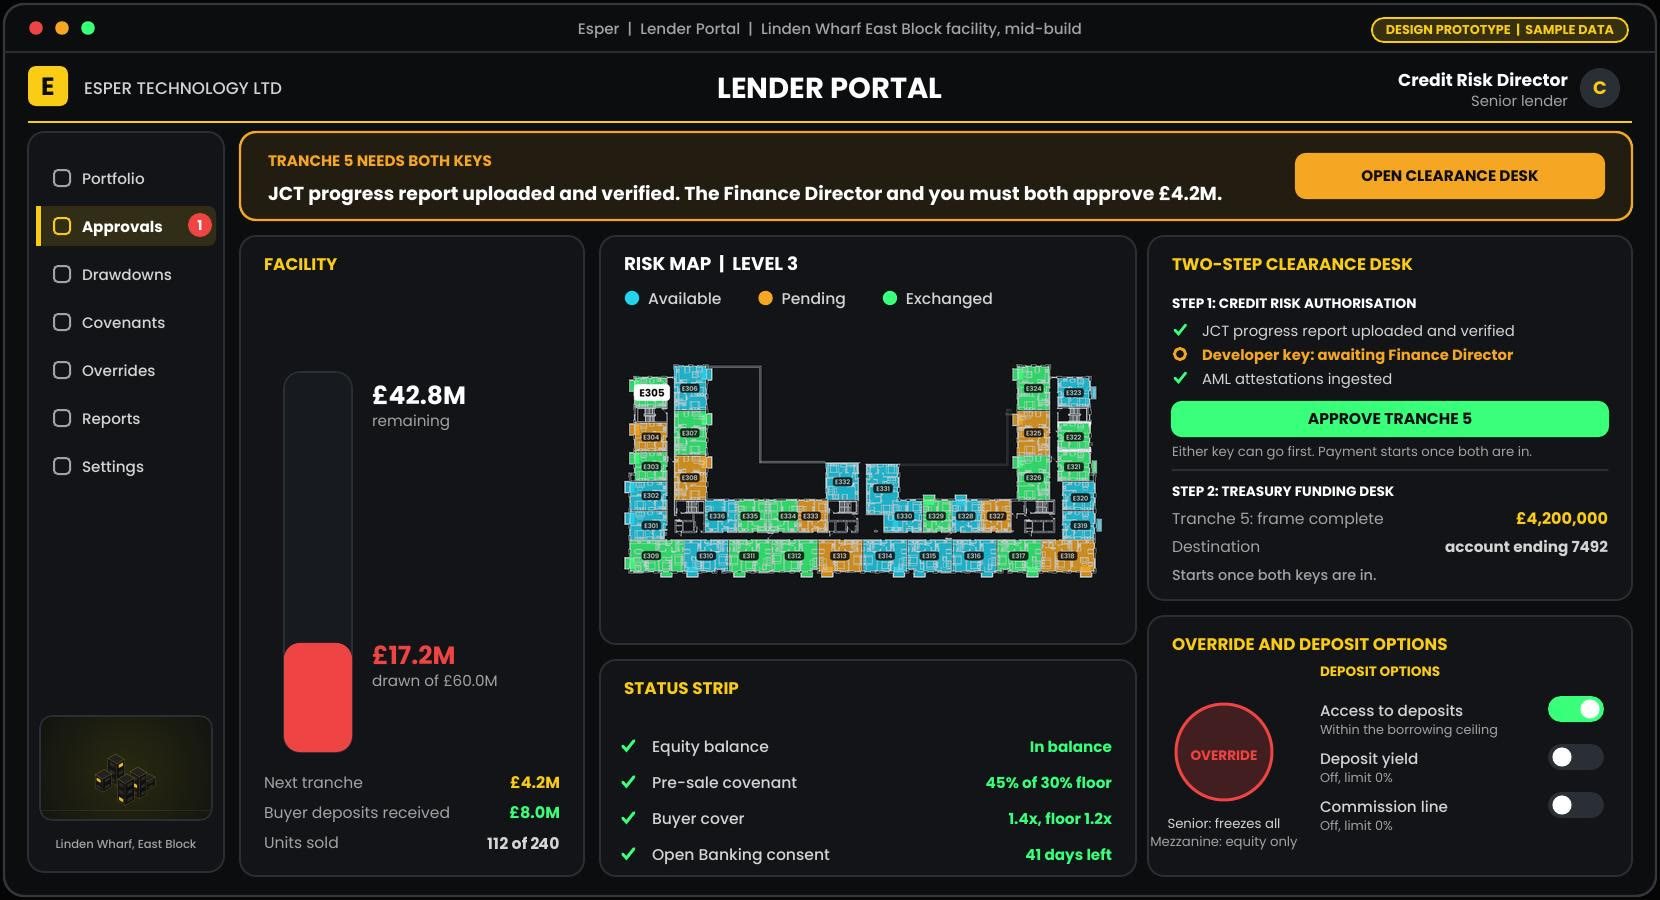
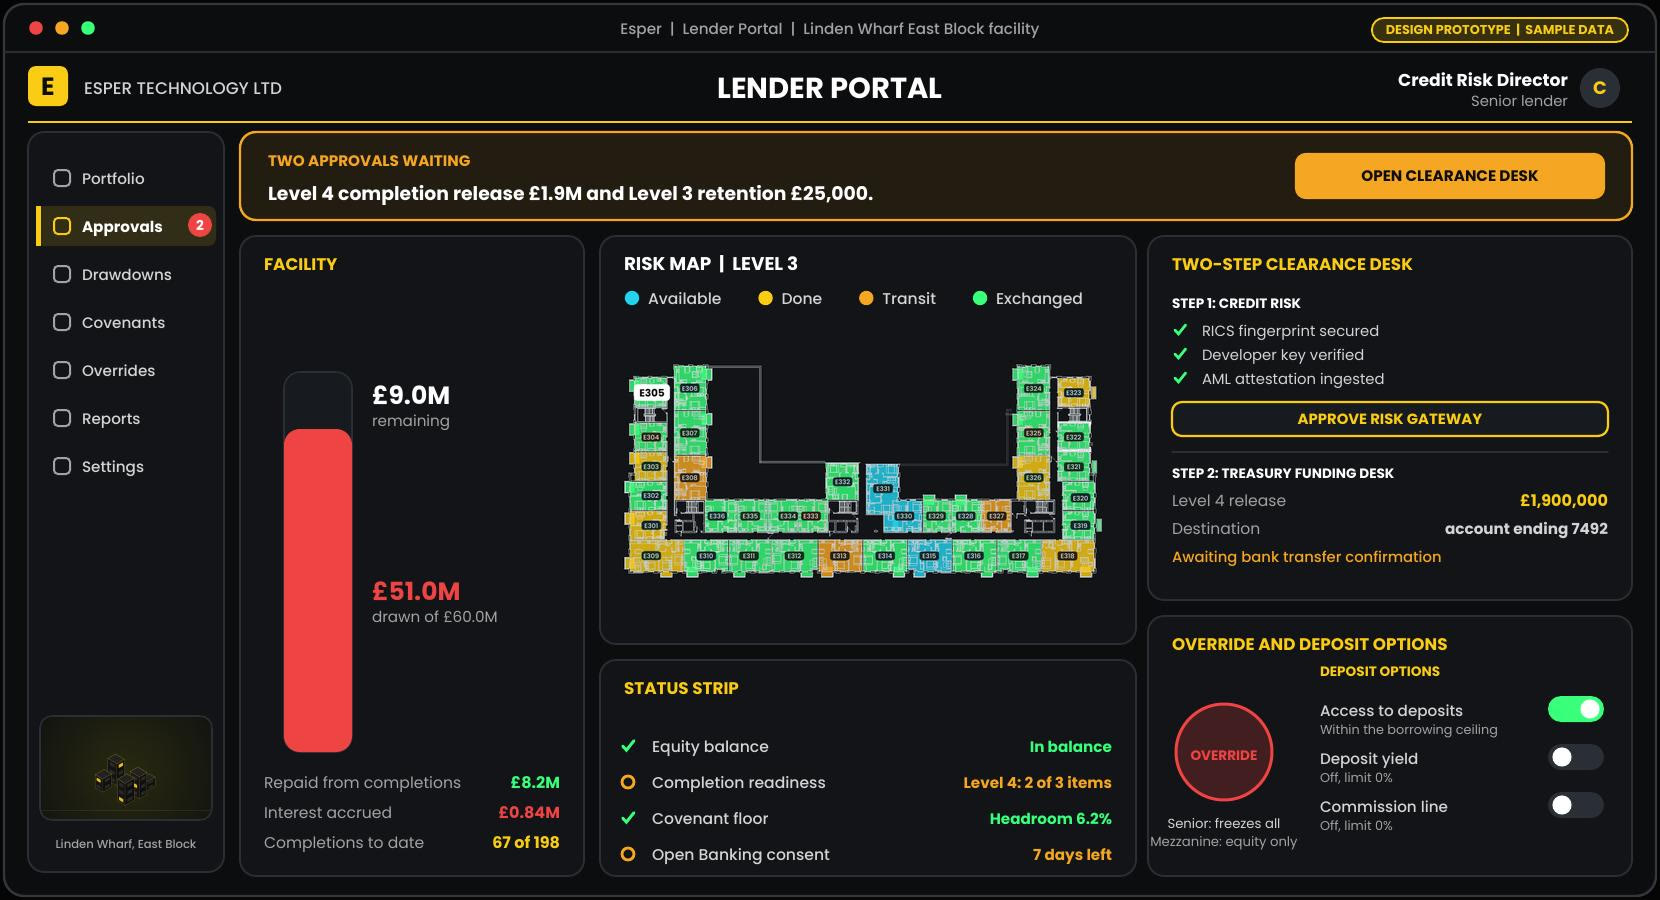
For larger off-plan sites, you log in to each scheme's own portal, with the facility, risk map, buyer deposits, two-step clearance desk and override switch for that site.
No lender wants a site in administration, especially a large one. Receivers, a stalled site, unhappy buyers and months of recovery work all eat into the loan. The earlier you know about a problem, the more ways there are to fix it.
A cash shortfall or a slipping programme often only shows up at the next site visit or monthly report. By then the developer has fewer options, and so do you.
Cash running short, spend drifting from budget, a missed milestone or a pre-sale covenant slipping: you see it the day it happens, with time to work out a solution with the developer.
Early warning gives you room for extra equity, a revised programme or a restructure before the site stalls.
A site that keeps moving holds its value. A stalled site and an insolvency process rarely do.
Fewer failed schemes means fewer buyers out of pocket, and fewer headlines with your name in them.
One live view of progress, cash and sign-offs across every scheme you fund.
Open banking confirms the cash and the surveyor signs off the stage, so approvals take minutes, not days of chasing.
See when a scheme drifts from plan before it becomes a problem, not after the next site visit.
Zero manual re-keying and no forged PDFs, so the same team can safely handle more loans.
Your warehouse and senior funders can see the same verified record, so they have less reason to charge you a premium.
Reward well-run schemes with sharper terms, with the data to back your credit decisions.
Illustrative example only.
The senior lender's risk team can freeze or recalibrate a facility in real time, based on live data. Where there's a mezzanine lender, it holds a sub-override over its own position. Your treasury still makes every payment. Insurers see the same verified record but never control it.
For lenders with many loans, the portfolio desk shows the whole book and brings forward only broken conditions and actions due, so your team spends its time where the risk is.
The surveyor's report goes in first. The developer's Finance Director and your credit team each approve. Your treasury pays through your own channels, as now.
Either key can go first. Esper never holds or moves money.
Agree the rules at the start, such as pre-sale covenants, buyer cover floors and equity balance. Esper checks them continuously and alerts every party at once if one slips.
The lender or insurer sets the rules and the terms. Esper reports the facts.
Design prototype with sample data.
A one-page letter of intent. No cost, no commitment, and you can walk away at any time.
Priority onboarding and preferential terms when Esper rolls out.
See the technology working on a real scheme, one to one.
Our films show what Esper does. The live demo shows the product working on a scheme: the dashboards, the alerts and the shared record. While our patents are pending, we show it one to one to registered partners.