For developers

Prove you run a good scheme, and get paid for it.

A careful driver with a black box pays less for insurance. With Esper, your lender, surveyor, insurer and buyers all see verified progress and cash on your scheme, so you have the evidence to ask for better terms.

Free, non-bindingEsper never holds or moves money

Esper for developers · 1:20

Two ways to work with Esper

Simple for smaller schemes. Bespoke for larger ones.

Free to youBridging portal

Smaller developers

For schemes funded by a bridging lender, without off-plan buyers.

  • Totally free to the developer. Your lender covers the cost.
  • A simpler model: upload, approve, get funded.
  • Faster drawdowns, because your lender sees verified progress and cash.
  • A verified track record to take to your next lender.
£10m to £100m+ GDVOff-plan development portal

Larger off-plan developers

For schemes with off-plan buyers, senior debt and insurers.

  • Bespoke deal structures, set up around each scheme.
  • Better oversight: plot-by-plot tiles change colour as units are reserved, exchanged and completed.
  • Buyer portal showing deposit cover and verified progress, so buyers commit sooner.
  • Health check, monitored terms and two-key drawdowns.
Protect your scheme

Spot problems early, and solve them with your lender.

Every development hits problems: a cost overrun, a contractor issue, slower sales. What matters is how early they're spotted. When a lender finds out late, options narrow fast, and the worst case is administration. Nobody wants that, least of all you.

Today

Your lender finds out late.

Problems often reach the lender at the next site visit or monthly report, by which point trust is strained and choices are limited.

Problem startsLender finds out
With Esper

You both see it straight away.

Your cockpit flags the issue the day it happens, and your lender sees the same facts. You can agree a fix together while there's still time and money to act.

Problem startsBoth alerted

A lender on your side

Lenders work with developers who are open with them. A shared, verified record builds that trust from day one.

Room to fix it

Early warning leaves time for extra equity, a revised programme or a restructure, before the site stalls.

Protect your equity and name

Keep the scheme moving and avoid the cost, delay and reputational damage of administration.

What changes for you

Less chasing, more building.

Potentially cheaper finance

A verified track record gives you the evidence to negotiate better rates and fees with your lender.

Potentially cheaper cover

Warranty and insurance providers can price on data, the way black-box car cover does.

Faster drawdowns

Lenders see the risk for themselves, so money arrives in days, not weeks.

A better-run scheme

Your site, sales and finance teams work from one record instead of email chains and spreadsheets.

Faster off-plan sales

Buyers commit sooner when they can watch their home being built and see their deposit is protected.

A smaller completion cliff

Completions line up sooner, so you spend less time at peak debt paying interest.

Potential savings only. Finance and insurance terms are always the lender's and insurer's decision.
Before and after

From paperwork to proof.

Today

Paper and email chains

Monitoring reports arrive late, bank statements are checked by hand, and everyone pays for the uncertainty in rates, premiums and delays.

Drawdown requestWeeks
With Esper

One shared, verified workflow

Open banking confirms the cash, the surveyor signs off the stage, and the lender sees it the moment it happens.

Drawdown requestDays
Where the cost comes from

Interest leaks out at both ends of a scheme.

For growing boutique and mid-market developers, administrative delay and unpriced uncertainty drain cash from both ends of the development cycle.

The back end: lender delay

Drawdowns wait on paper.

Senior lenders hold monthly drawdowns while manual checks run their course. Three to four weeks per tranche creates cash crunches on site while interest compounds.

The front end: buyer delay

Completions drift.

At practical completion, off-plan buyers and their brokers often take two months or more to finalise mortgages, while peak senior debt keeps compounding.

An extra saving at the end of every scheme. On £10m of peak debt at 9%, each month of completion delay costs about £75,000 (illustrative). When buyers and their brokers can see verified progress months ahead, valuations and mortgage offers can be lined up before handover.
The health app for property development

See how your scheme compares.

A health app is something you check every day, because it tells you how you're doing and how you compare. Every Esper scheme adds verified data, so you can see where you sit against similar schemes and what to fix first. The longer you use it, the more valuable your history becomes.

Scheme health check · Riverside Court (example)
MeasureYouMedianWhere you sit (worse → better)Percentile
Sales velocityplots exchanged a month, higher is better3.22.6
71th
Deal structure and safetylowest buyer cover, higher is better1.1x1.3x
25th
Drawdown waitdays per tranche, lower is better2317
30th
Completion cliffaverage days late, lower is better3524
28th
Cost of salesshare of GDV, lower is better6.5%7.0%
66th
Profit marginshare of GDV, higher is better21.0%19.0%
74th

Illustrative example. Benchmarks use anonymised data from at least five similar schemes. Your own figures are never shown to anyone else.

Monitored terms

The telematics reward.

Like a telematics policy, a lender or insurer can choose to offer better terms to schemes that keep to rules agreed at the start: for example, buyer cover above the lender's floor and every payment referenced. Esper checks the rules continuously.

MonitoredAll agreed rules met. The scheme qualifies for the better terms.
At riskA rule has slipped. Everyone is told at once, with time to put it right.
LapsedNot fixed in time. Standard terms apply.

The lender or insurer sets the rules and the terms. Esper reports the facts.

Two keys

Faster drawdowns, without losing control.

Before any tranche is released, the Finance Director and the lender each approve it on screen. No chasing, no re-keying.

  1. Surveyor uploadsThe monitoring surveyor's progress report is uploaded and fingerprinted.
  2. Developer approvesThe Finance Director approves with multi-factor sign-in.
  3. Lender approvesThe lender's credit team approves in its own portal.
  4. Lender paysTreasury makes the transfer through its own banking channels.
  5. Esper confirmsThe status turns green when the funds arrive.

Either key can go first. Esper never holds or moves money.

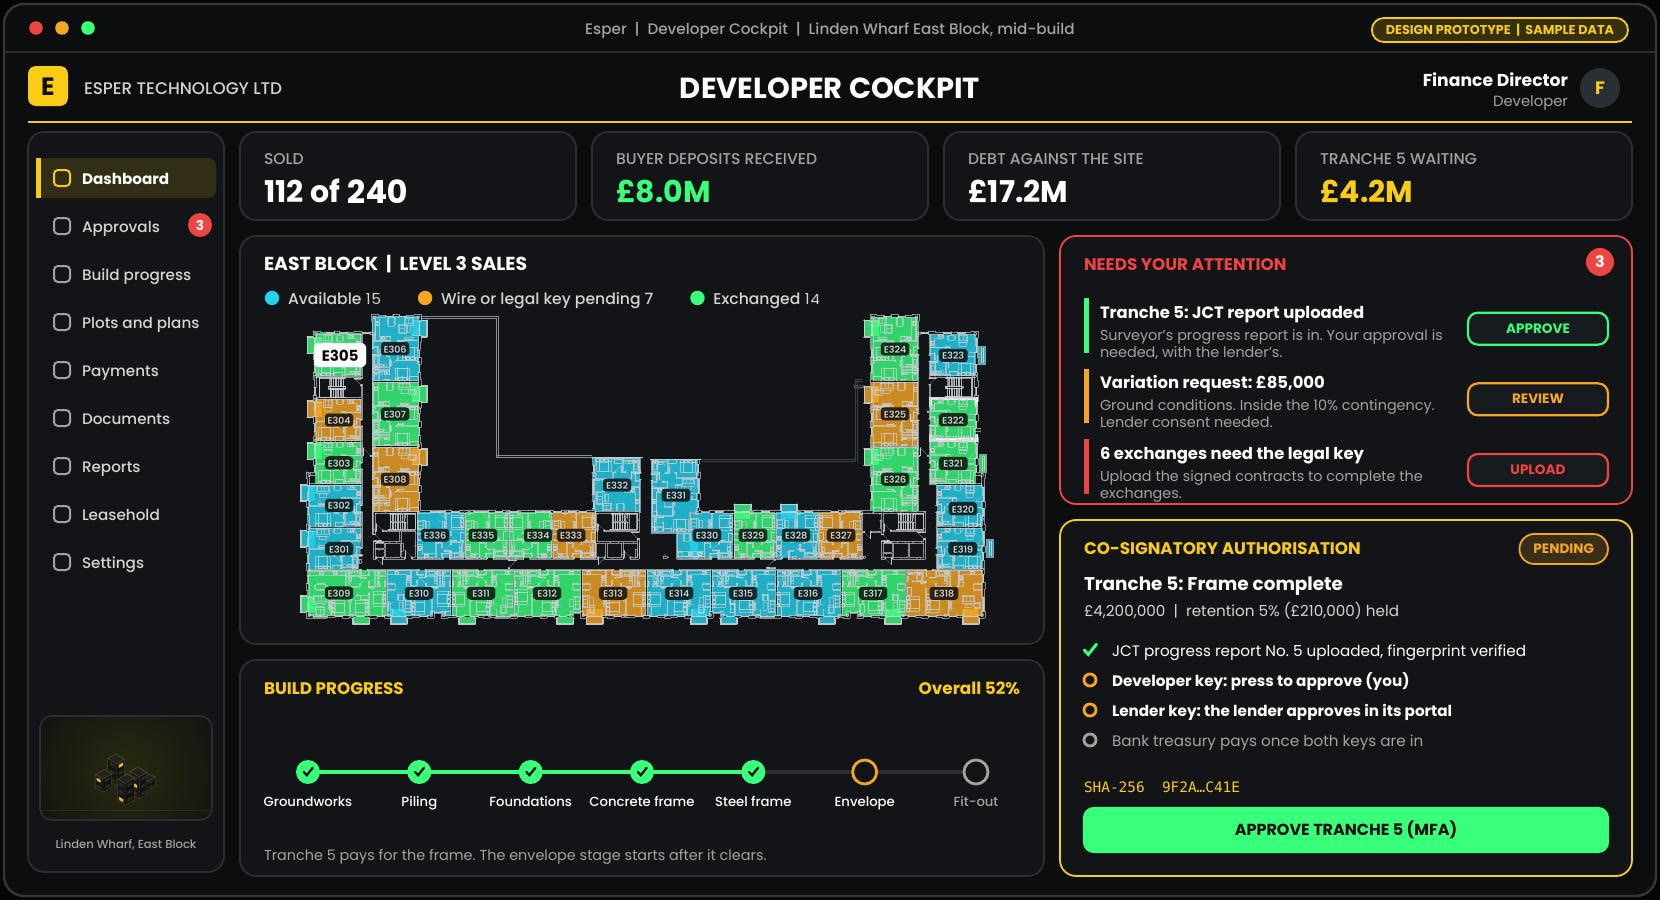
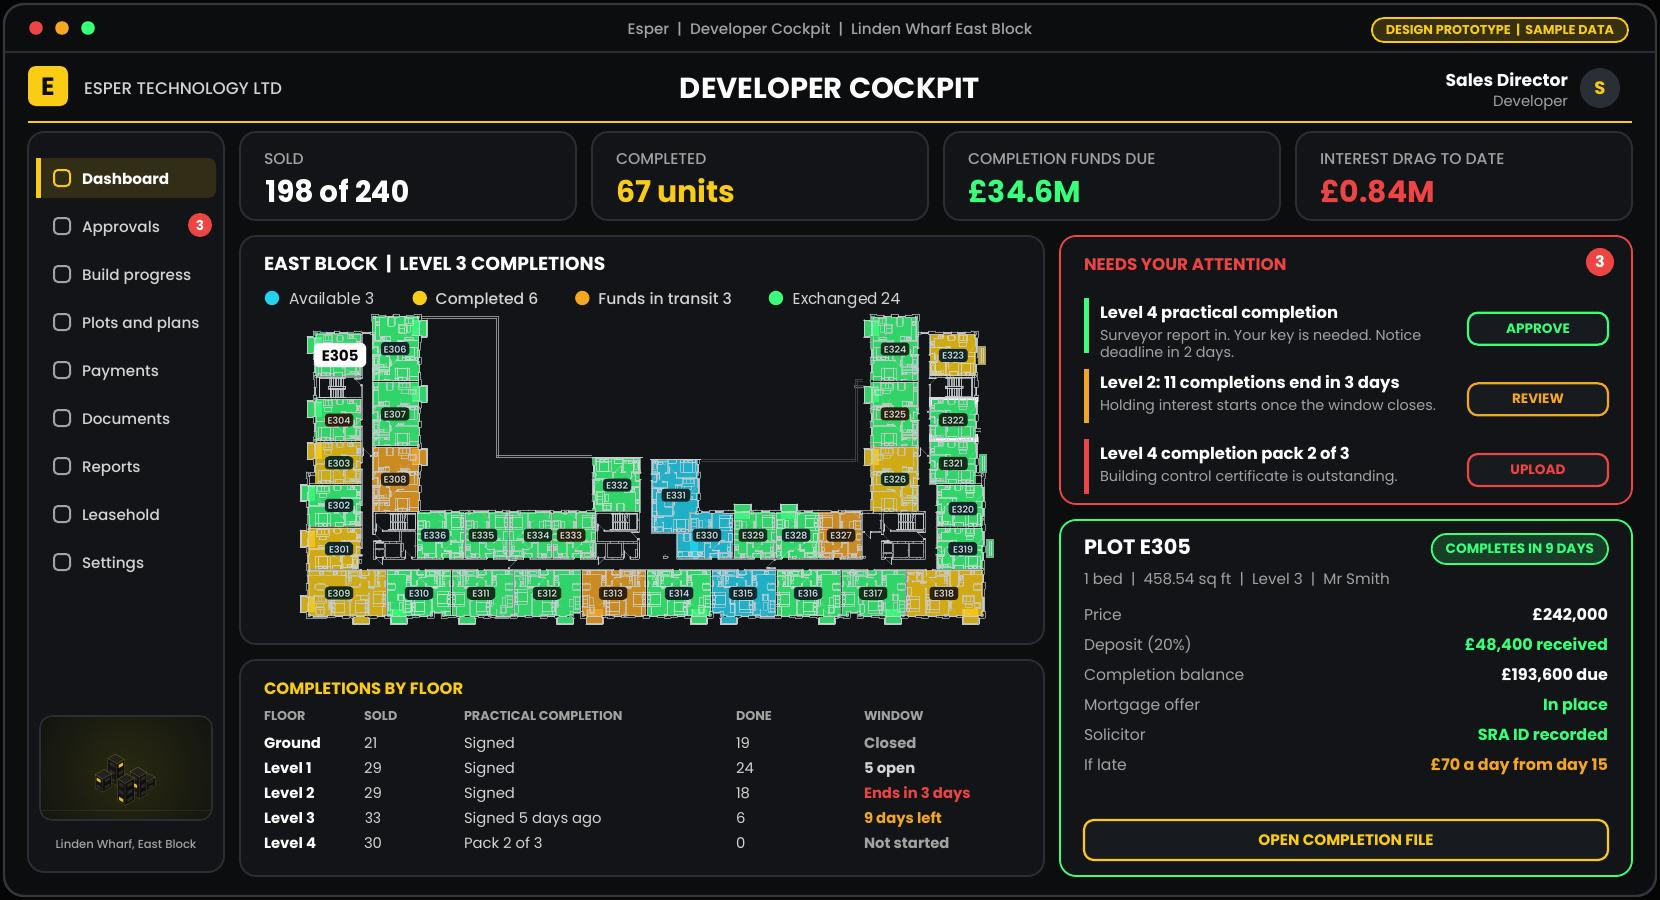
Product preview

Your developer cockpit.

Developer cockpit mid-build showing plot sales, tranche status and approvals
Mid-build Plot-by-plot sales, pricing and milestone tracking in one shared view.
Developer cockpit at completion showing completions by floor and urgent approvals
At completion Completions by floor, urgent approvals and the plot file.

Design prototype with sample data.

A badge of institutional competence

Show buyers and funders you have nothing to hide.

Sell sooner

More buyers decide sooner.

The biggest barrier to off-plan sales is fear of developer insolvency. Showing buyers how their deposit is covered, and verified progress, gives them a reason to choose your scheme from the first reservation, and helps you meet pre-sale lender quotas sooner.

Looking ahead

Ready for institutional money.

Institutional investors want verified data before they commit. Founding developers build that track record from their first scheme. See where Esper is heading →

Founding partner programme

Become a founding partner.

Free, non-binding LOI

A one-page letter of intent. No cost, no commitment, and you can walk away at any time.

Founding partner terms

Priority onboarding and preferential terms when Esper rolls out.

Private demo

See the technology working on a real scheme, one to one.

  • Free and non-binding
  • Keep your current lender, surveyor and solicitor
  • Limited number of founding schemes
Register free
See the tech in action

The full product demo is private.

Our films show what Esper does. The live demo shows the product working on a scheme: the dashboards, the alerts and the shared record. While our patents are pending, we show it one to one to registered partners.

I'd like
Free and non-binding. We only use your details to contact you about Esper. See our privacy notice.